You open your brokerage app, tap on a stock you like, and hit the options chain for the first time. Rows of strike prices. Columns of bids, asks, deltas and expiry dates. Somewhere in there, you have heard, are strategies that can generate income, protect your portfolio or let you take a position with a fraction of the capital.
But which one do you actually start with?
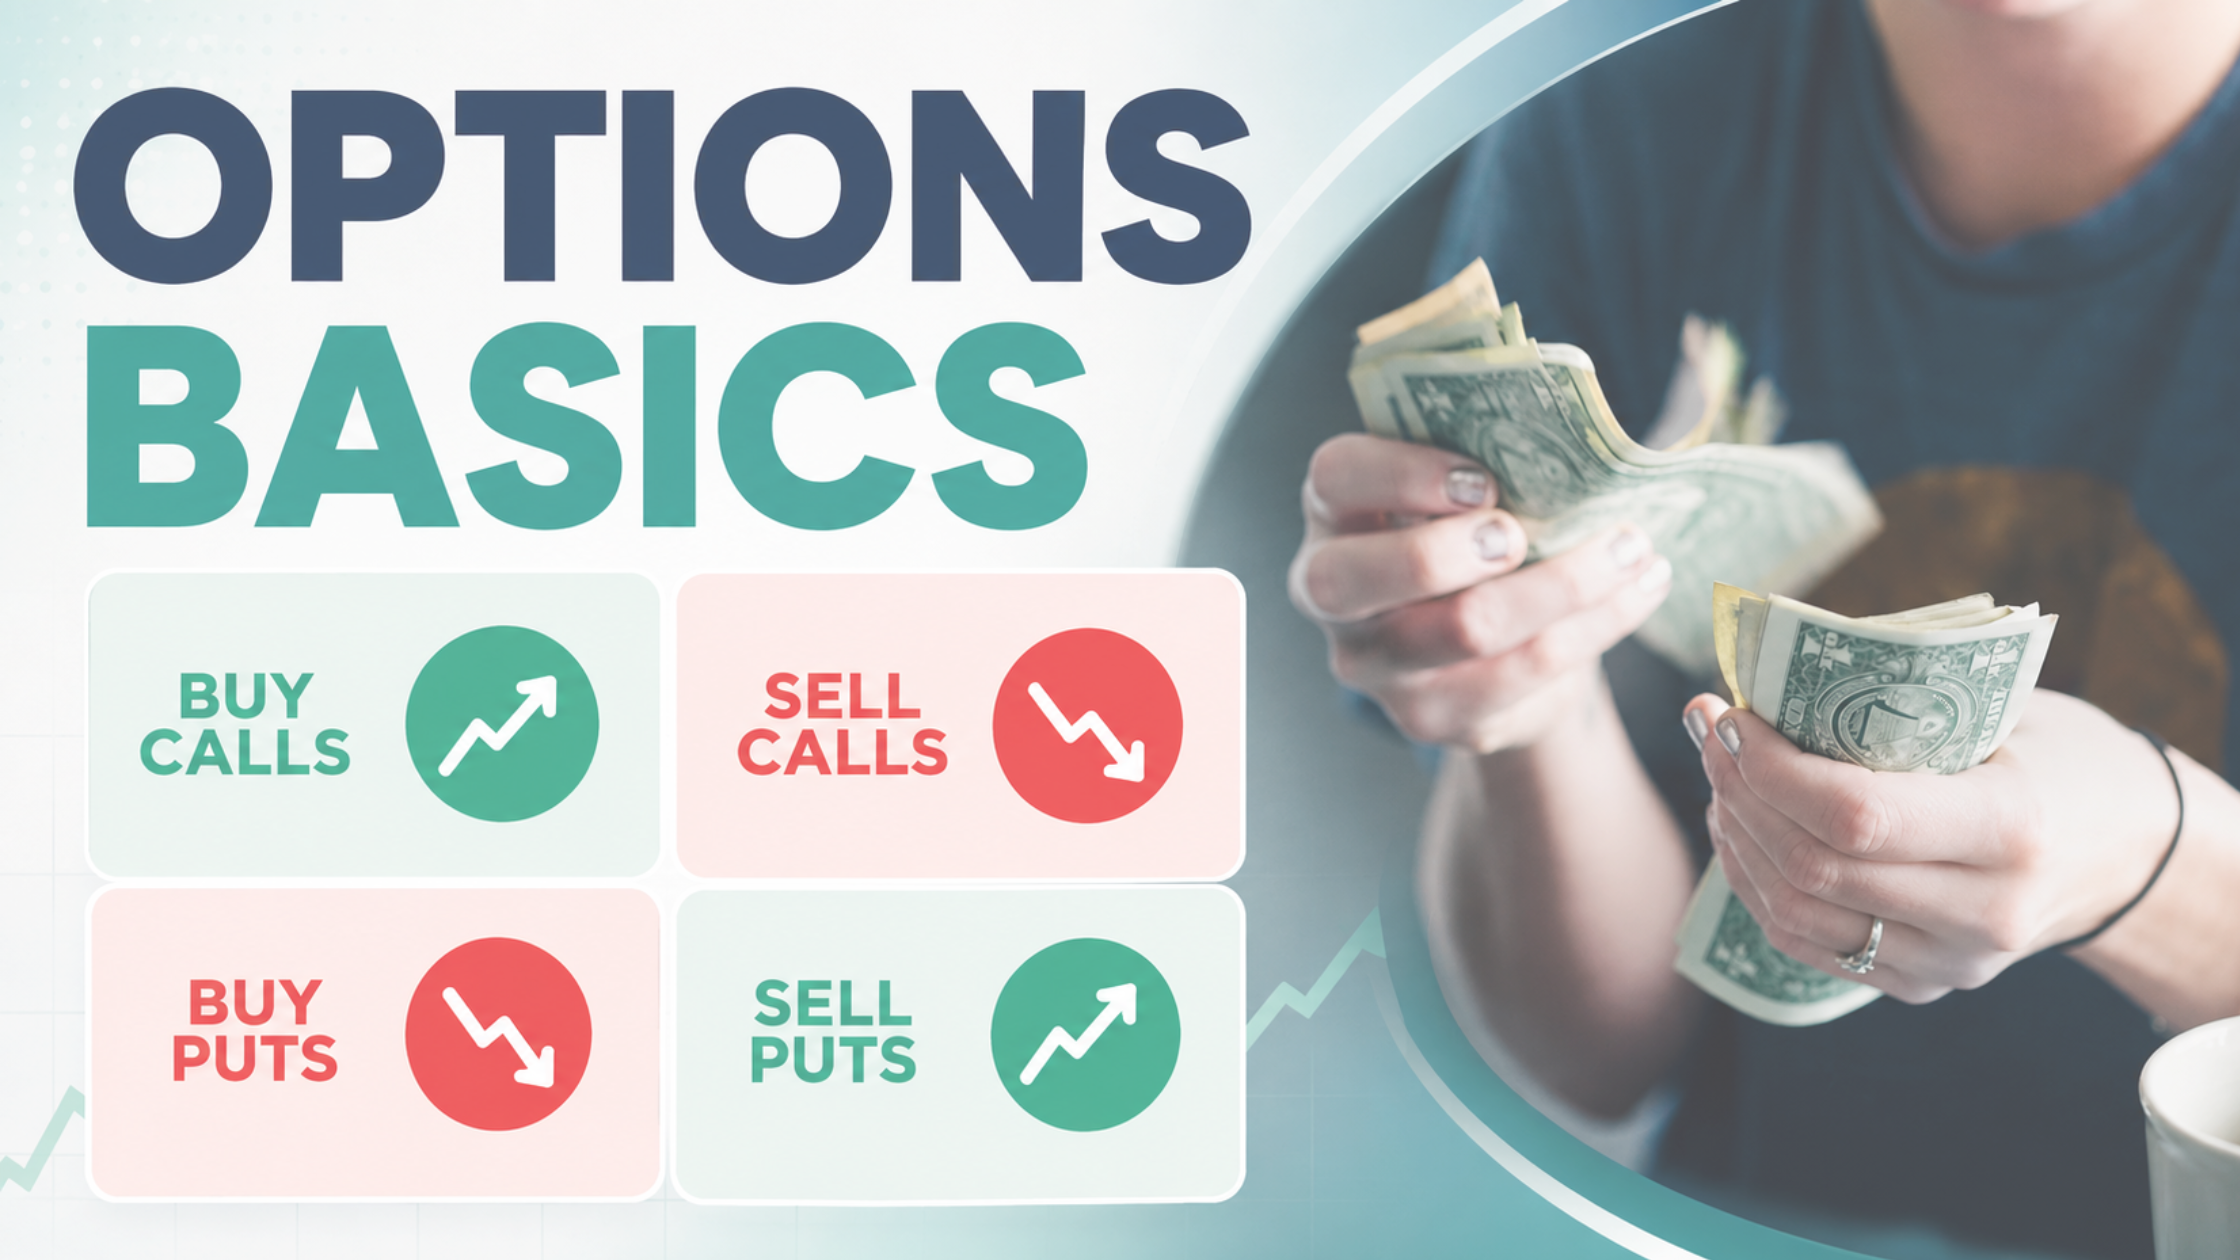
Here is the short answer for any aspiring options trader: the best beginner options strategies are the ones with defined risk, few moving parts and a clear reason for using them. For most beginners, that usually means starting with covered calls and cash-secured puts on stocks you would be happy to own, then moving on to more complex options contracts.
In this guide, we rank seven strategies from most beginner-friendly to more advanced, show you exactly how each one works with examples, and walk through the outcomes.
Options trading involves risk, and you can lose money with every strategy in this article. Our goal is to help you understand those risks before you place a single trade. Because knowing the possible outcomes before you trade, will make you a better trader. Treating option trading as a probabilistic exercise tends to deliver better results than simply trading because trader think the stock will go up or down.
New to calls and puts? Watch this full beginner lesson first, then come back to the strategies below.
"Best" means very little unless you know what it is measured against. We ranked each strategy on four things that matter most when traders are starting out.
If you need a refresher on the building blocks (calls, puts, strike prices, premiums and expiry), start with our complete options trading for beginners guide and our calls and puts explained with examples.
One note before we dive in: one standard US equity option contract represents 100 shares. So a premium quoted at $1.50 means $150 per contract.
|
Strategy |
Market View |
Max Loss |
Max Gain |
Capital Needed |
Complexity |
|---|---|---|---|---|---|
|
Covered call |
Neutral to mildly bullish |
Stock falls (cushioned by premium) |
Capped at strike plus premium |
100 shares |
Low |
|
Cash-secured put |
Neutral to bullish |
Strike price minus premium (if stock goes to zero) |
Premium received |
Cash to buy 100 shares |
Low |
|
Protective put |
Bullish, wants protection |
Limited to stock drop to strike plus premium |
Unlimited (less premium) |
100 shares plus premium |
Low |
|
Long call |
Bullish |
Premium paid |
Unlimited in theory |
Premium only |
Low to medium |
|
Long put |
Bearish |
Premium paid |
Substantial (stock falls to zero) |
Premium only |
Low to medium |
|
Bull call spread |
Moderately bullish |
Net debit paid |
Strike width minus debit |
Net debit |
Medium |
|
Bull put spread |
Neutral to bullish |
Strike width minus credit |
Net credit received |
Strike width (margin) |
Medium |
You may notice something similar in every strategy here. It has a maximum loss you can calculate before you enter. That is deliberate. Strategies with undefined or unlimited risk, like selling naked calls, are not on this list, and we explain what those are later.
All examples below use a hypothetical stock, ABC, trading at $50. The premiums are for illustration only. Real premiums depend on volatility, time to expiry and market conditions.
What it is: You own 100 shares of a stock and sell one call option against them. You collect a premium upfront in exchange for agreeing to sell your shares at the strike price if the stock rises above it by expiry.
When traders use it: You already hold a stock, you are neutral to mildly bullish on it, and you would be comfortable selling at a higher price.
Worked example: You own 100 shares of ABC, bought at $50 per share. You sell one 30-day $55 call for $1.50, collecting $150 since 1 contract is 100x shares.
Scenario A (ABC closes at $53): The call expires worthless. You keep the $150 premium and your shares, now worth $5,300. Total gain on paper: $300 from the shares plus $150 premium, or $450. This is also the maximum profit from selling a call.
Scenario B (ABC rallies to $62): Your shares are called away at $55. You make $500 on the shares plus $150 premium, a total of $650. But if you had not sold the call, you would have made $1,200. That gap is the opportunity cost of a covered call. So while you made money in selling calls, you could have made more just simply holding on to the stock.
Scenario C (ABC falls to $42): The call expires worthless and you keep the $150 premium. But your shares have lost $800, so your net position is down $650. Your breakeven is $48.50 ($50 minus $1.50). So while the premium helps to cushion your stock from falling, you still have made a loss from actually holding on the underlying stock.
Key risk: A covered call does not protect you from a falling stock. The premium only cushions a small drop. Your upside is also capped. And that is why traders tend to use it when they are neutral to mildly bullish on a stock.
Go deeper: Covered calls explained and when to roll covered calls.
What it is: You sell a put option and set aside enough cash to buy 100 shares at the strike price if you are assigned. You collect a premium for taking on that obligation.
When traders use it: There is a stock you would like to own, but at a lower price than today's. Instead of waiting with a limit order, you get paid while you wait.
Worked example: XYZ trades at $50. You sell one 30-day $47 put for $1.20, collecting $120. Your broker reserves $4,700 in cash.
Scenario A (XYZ stays above $47): The put expires worthless. You keep the $120, a 2.6% return on the cash reserved over 30 days in this hypothetical example. Your cash is released.
Scenario B (XYZ drops to $43): You are assigned and buy 100 shares at $47. Because you received $1.20 in premium, your effective cost is $45.80 per share. With XYZ at $43, you are down $280 on paper. Your breakeven is $45.80.
Key risk: If the stock falls sharply, you are still obligated to buy at the strike price. The premium only offsets part of the decline. So most traders only sell puts on stocks you would genuinely be comfortable holding. Selling a cash secured put also locks in capital making traders less agile.
Go deeper: The beginner guide to selling cash-secured puts.
Adam Khoo explains how he thinks about selling puts on stocks he wants to own.
What it is: You own 100 shares and buy a put option on the same stock. The put acts like an insurance policy, giving you the right to sell your shares at the strike price no matter how far the stock falls.
When traders use it: You want to keep holding a stock through an uncertain period (an earnings release, a volatile market) but want to limit how much you could lose.
Worked example: You own 100 shares of ABC at $50. You buy one 60-day $45 put for $1.50, paying $150.
Scenario A (ABC rises to $58): The put expires worthless. Your shares gained $800, minus the $150 cost of protection, for a net gain of $650.
Scenario B (ABC falls to $38): Your shares have lost $1,200. But your put is now worth $7 per share ($700). Your net loss is $1,200 minus $700 plus the $150 you paid, or $650. That is your maximum possible loss in this trade, no matter how far ABC falls.
Key risk: Protection costs money. If the stock does not fall, the premium is a drag on your overall portfolio returns, and buying protection repeatedly adds up.
Go deeper: Covered call and protective put.
What it is: You buy a call option, giving you the right (not the obligation) to buy 100 shares at the strike price before expiry. It is a bullish position that needs far less capital than upright buying the shares, but it comes with its own drawbacks.
When traders use it: You expect a stock to rise meaningfully within a specific time frame and want limited, defined risk.
Worked example: ABC trades at $50. You buy one 60-day $52 call for $2.00, paying $200. Your breakeven at expiry is $54 ($52 strike plus $2 premium).
Scenario A (ABC rises rapidly to $58 at expiry): Your call is worth $6 per share ($600). Your profit is $400 on a $200 outlay.
Scenario B (XYZ ends at $51): The stock went up, but not above your strike. The call expires worthless and you lose the full $200.
Key risk: You need to be right about direction, size of the move and timing. Time decay (theta) erodes the option's value every day, this means that everyday the contract loses value, because you have less time left to be “right”. While buying calls is a simple mechanism, it should be used carefully and smartly. Instead of a way to “hit a jackpot”.
What it is: You buy a put option, giving you the right to sell 100 shares at the strike price. It profits when the stock falls.
When traders use it: You expect a stock to decline and want a bearish position with defined risk, without short-selling shares.
Worked example: ABC trades at $50. You buy one $48 put for $1.50, paying $150. Your breakeven is $46.50.
Scenario A (ABC falls to $42): Your put is worth $6 per share ($600). Profit: $450.
Scenario B (ABC stays at $49): The put expires worthless and you lose $150.
Key risk: Same as long calls. Time decay works against you, and a stock that drifts sideways or falls too slowly can still cost you the full premium. You may be right with the direction but if time is not on your side, you still lose the premiums.
What it is: You buy a call at a lower strike and sell a call at a higher strike, same expiry. The call you sell reduces the cost of the one you buy, in exchange for capping your upside. This is a debit spread.
When traders use it: You are moderately bullish and want a cheaper, defined-risk alternative to a long call.
Worked example: ABC trades at $50. You buy the $50 call for $3.00 and sell the $55 call for $1.20. Your net cost (debit) is $1.80, or $180. Your breakeven is $51.80.
Scenario A (ABC closes at $57): The spread reaches its maximum value of $5 (the width between strikes). Your profit is $500 minus $180, or $320.
Scenario B (ABC closes at $49): Both calls expire worthless. You lose the $180 you paid, which is your maximum loss.
Key risk: Your gains are capped at $320 no matter how high XYZ goes, and your losses are capped at $180. With two legs, you also have more to manage, especially if the stock finishes between the strikes.
Go deeper: Bull call spread definition.
What it is: You sell a put at a higher strike and buy a put at a lower strike, same expiry. You collect a net premium (a credit), and the put you buy caps your maximum loss. Think of it as a cash-secured put with built-in protection and much less capital required.
When traders use it: You are neutral to bullish and want to collect premium with a clearly defined maximum loss.
Worked example: ABC trades at $50. You sell the $47 put for $1.40 and buy the $45 put for $0.60. You collect a net credit of $0.80, or $80. Your broker may typically requires the $200 strike width as collateral. Your breakeven is $46.20.
Scenario A (ABC stays above $47): Both puts expire worthless. You keep the $80.
Scenario B (ABC falls to $43): Both puts are in the money. Your loss is the $200 width minus the $80 credit, or $120. That is your maximum loss.
Key risk: Your maximum loss ($120) is larger than your maximum gain ($80). Credit spreads often win small and lose bigger, so position sizing and trade management matter a lot.
Go deeper: Put credit spread explained and credit spread vs covered call vs cash-secured put.
Once you are comfortable with cash-secured puts and covered calls (the two basics we talked about), you may notice they fit together quite naturally. That combination is called the wheel strategy.
The wheel is popular with beginners because it uses the two simplest strategies on this list. But it carries the same core risk as both: if the stock falls sharply after assignment, premiums will not make up for the loss. Read our full beginner's guide to the wheel strategy for a complete worked cycle.
|
If your goal is to... |
Strategy to study first |
|---|---|
|
Earn income on shares you already own |
Covered call |
|
Buy a stock you like at a lower price |
Cash-secured put |
|
Protect gains on a stock you are holding |
Protective put |
|
Take a bullish position with limited capital |
Long call or bull call spread |
|
Take a bearish position without shorting |
Long put |
|
Collect premium with a defined maximum loss |
Bull put spread |
Based on our experience here is the trap beginners tend to fall into: they choose a strategy based on how much it could make, not on how well they understand what could go wrong.
Long calls are the classic example. A $200 bet that could turn into $600 feels exciting. A ROI of 3x. But when that call expires worthless three times in a row, many traders either give up on options entirely or start sizing up to "win it back." Neither ends well.
Income strategies have their own trap too. Covered calls and cash-secured puts can feel like free money after a string of small wins. Then one sharp sell-off wipes out months of premium, and the trader realises they were picking up coins without respecting the risk underneath.
The reframe that changes everything: process beats prediction. You do not need to predict every move. You need a strategy you understand, a position size you can live with if the worst case happens, and a plan for what you will do before you enter. Then run and track your performance in the long run before analysing how to improve. Starting a trade journal when trading options is almost a necessity as it helps traders understand the mechanics behind every contract traded.
Lastly, disciplined traders know their maximum loss before they execute, never after.
Just as important as what to learn first is what to leave alone until you have real experience.
Selling a call without owning the shares exposes you to theoretically unlimited losses, because there is no ceiling on how high a stock can rise. Most brokers restrict this to their highest approval levels for good reason. Read more on why naked/uncovered calls are dangerous for beginners.
A $0.10 option looks like a bargain. But it is cheap because the market sees a low probability of it ever being worth anything. Buying these repeatedly is closer to buying lottery tickets than trading with a plan.
Options that expire the same day have grown popular, but they move extremely fast. Prices can swing dramatically within minutes, and there is no time to recover from a mistake.
Even a defined-risk strategy can do serious damage if you put too much of your account into one trade. Many traders cap the risk on any single trade to a small percentage of their account.
This depends heavily on the strategy, and it is where many beginners outside the US get caught off guard. US-listed equity options are priced in US dollars and standard contracts typically cover 100 shares.
Brokers also assign options approval levels that determine which strategies you are allowed to trade. Most brokers also require you have a margin account before trading options. Beginners usually start at a level that permits covered calls and cash-secured puts, with spreads unlocked at a higher tier. Check your broker's requirements, fees and the rules that apply where you live before you start.
Once you are comfortable with the strategies above, these are natural next steps:
There is no single best option strategy for every beginner. There is only the best strategy for your goal, your capital and your level of understanding right now.
Start with one. Learn it thoroughly, paper trade it, and understand every outcome, including the ones where you lose money. Then add the next. The traders who last in options are rarely the ones who found the most exciting strategy. They are the ones who respected risk from day one.
Piranha Profits® is one of the world’s leading online schools for investors and traders. In 2017, we started this online school to make our brand of online lessons and services available to people around the world. Headquartered in Singapore, we have since empowered the financial lives of over 20,000 students across 124 countries. The Piranha Profits® education team is led by award-winning financial mentor Adam Khoo, alongside 7-figure trading mentors Bang Pham Van and Alson Chew.
Get our latest investing & trading content



Piranha Profits® is a registered trademark in Singapore. © 2024 Piranha Ltd. All rights reserved.
submit your comment